Price cuts are turning up everywhere right now, and they read very differently depending on which side of the deal you’re on.Sellers tend to worry a cut means walking away with less than they
Dated: December 22 2023
Views: 91
When you read about the housing market, you’ll probably come across some information about inflation or recent decisions made by the Federal Reserve (the Fed). But how do those two things impact you and your homebuying plans? Here's what you need to know.
One of the Fed’s primary goals is to lower inflation. In order to do that, they started raising the Federal Funds Rate to slow down the economy. Even though this doesn’t directly dictate what happens with mortgage rates, it does have an impact.
Recently inflation has started to cool, a signal those increases worked and are bringing inflation back down. As a result, the Fed’s hikes have gotten smaller and less frequent. In fact, there haven’t been any increases since July (see graph below):
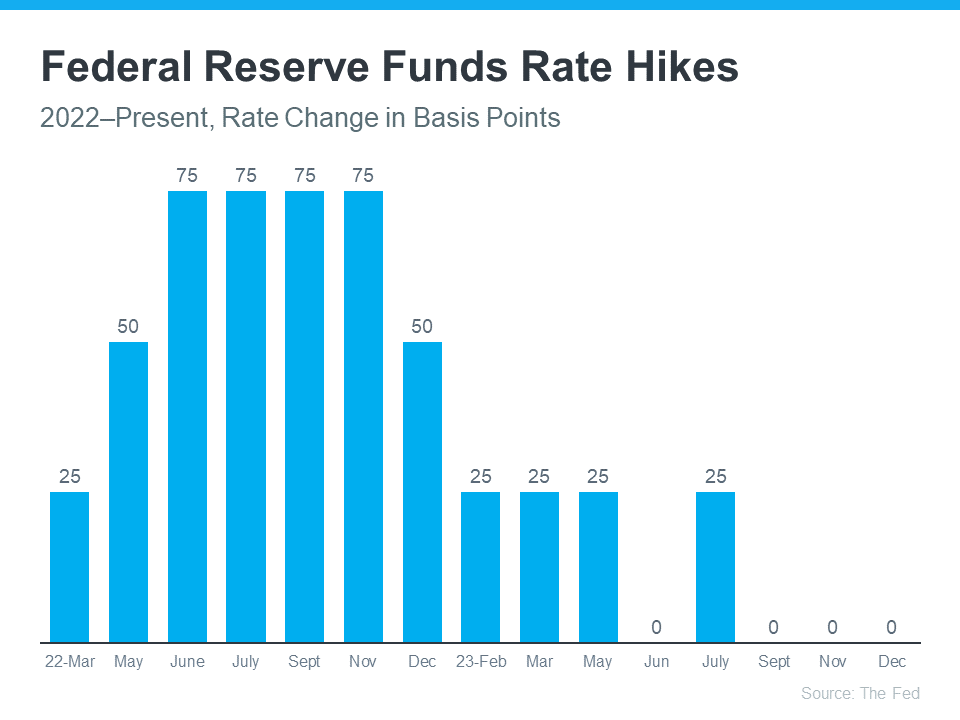
And not only has the Fed decided not to raise the Federal Funds Rate the last three times the committee met, they’ve signaled there may actually be rate cuts coming in 2024. According to the New York Times (NYT):
“Federal Reserve officials left interest rates unchanged in their final policy decision of 2023 and forecast that they will cut borrowing costs three times in the coming year, a sign that the central bank is shifting toward the next phase in its fight against rapid inflation.”
This indicates the Fed thinks the economy and inflation are improving. Why does that matter to you and your plans to buy a home? It could end up leading to lower mortgage rates and improved affordability.
Mortgage rates are influenced by a wide variety of factors, and inflation and the Fed’s actions (or as has been the case recently, inaction) play a big role. Now that the Fed has paused the increases, it looks more likely mortgage rates will continue their downward trend (see graph below):
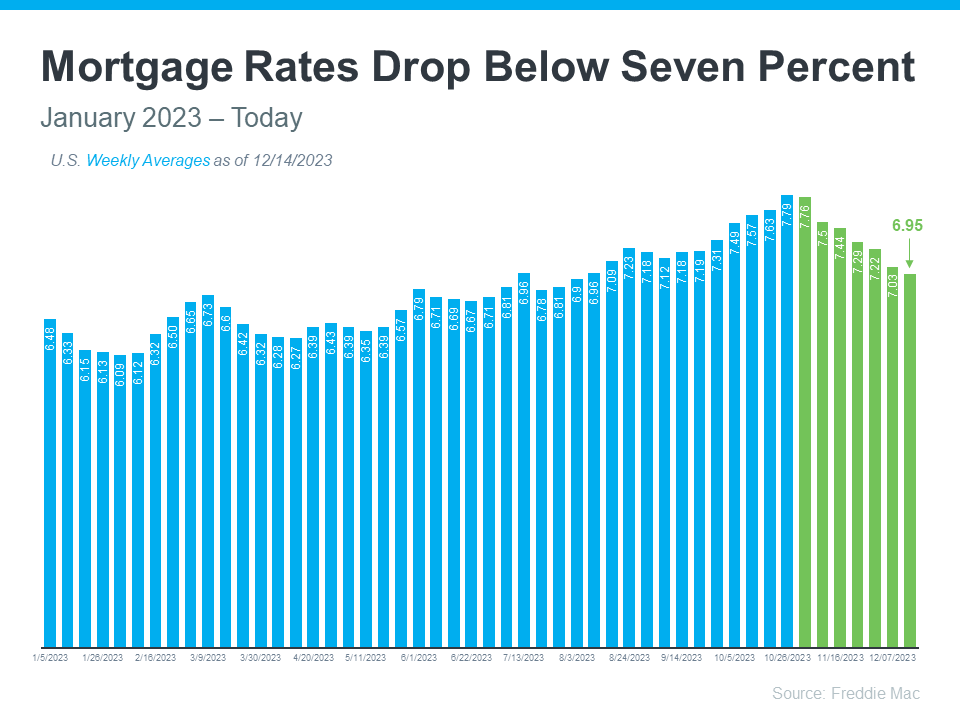
Although mortgage rates may remain volatile, their recent trend combined with expert forecasts indicate they could continue to go down in 2024. That would improve affordability for buyers and make it easier for sellers to move since they won’t feel as locked-in to their current, low mortgage rate.
The Fed’s decisions have an indirect impact on mortgage rates. By not raising the Federal Funds Rate, mortgage rates are likely to continue declining. Let’s connect so you have expert advice about changes in the housing market and how they affect you.
ENGLISHI’m Juan Carlos Hernandez Garza, your trusted guide to buying and selling real estate in the Vail Valley. For years, I’ve helped clients turn their mountain lifestyle dreams into re....
Price cuts are turning up everywhere right now, and they read very differently depending on which side of the deal you’re on.Sellers tend to worry a cut means walking away with less than they
If you're trying to buy a home, affordability is probably what keeps you up at night. And as you watch mortgage rates tick up again lately, it’s fair to wonder if you should just hit pause and
Today’s housing market splits into four distinct types. You’ve got cash buyers, buyers financing a purchase, owners who feel locked into a low rate, and builders with homes to sell.
Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.Yes, mortgage rates have been ticking up lately –
 IDX information is provided exclusively for personal, non-commercial use, and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information is deemed reliable but not guaranteed. Copyright © 2026 Vail Multi List, Inc. (VMLS)
The listing broker's offer of compensation is made only to participants of the MLS where the listing is filed.
